

As we look ahead to this week’s market action, we continue to monitor the overarching macro themes driving volatility: the health of the consumer in a rising rate environment, the ongoing AI story, and the implications of energy prices and the Middle East conflict on our wider portfolio.
But this week, the spotlight shifts squarely to earnings. We have a deluge of reports coming out, and it starts with the major U.S. financials.
FINANCIALS REPORT
All the banking heavyweights are reporting, including GS 0.00%↑ Goldman Sachs, JPM 0.00%↑ JPMorgan, MS 0.00%↑ Morgan Stanley, BLK 0.00%↑ BlackRock, STT 0.00%↑ State Street, and WFC 0.00%↑ Wells Fargo. These reports will give us a read into both the lending and trading environments.
My expectation is that this is a pretty sweet environment for banks and financials right now. Interest rates have come up, which directly bolsters their net interest income (NII). Meanwhile, on the consumer and credit default front, we have yet to see any major red flags.
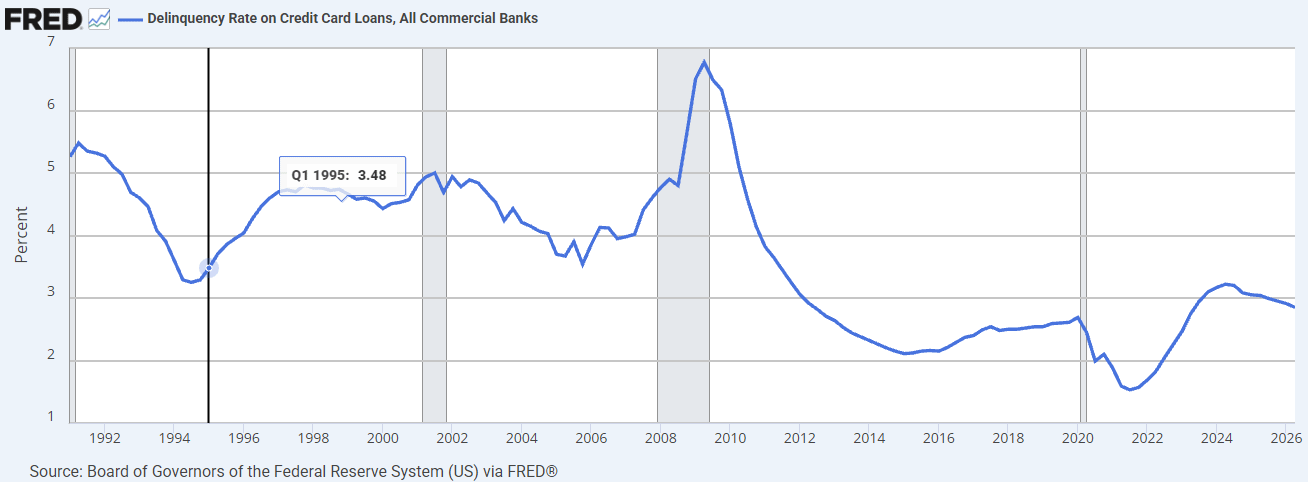
Add in the fact that market volatility remains high which is excellent news for their trading desks and the operational backdrop looks very strong. Last quarter was a record for most of these banks, and I suspect this quarter will look very similar. While some bank stocks pulled back recently (likely due to investors feeling they had run up a bit too fast), let’s see what their forward guidance tells us.
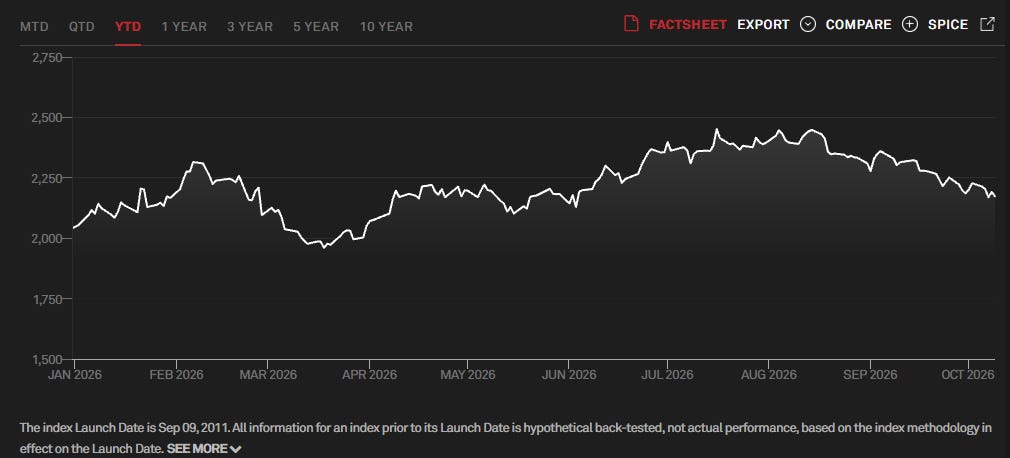
THE AI TRADE
We’re also getting crucial updates from the tech and semiconductor space, specifically TSMC, Samsung Electronics, and ASML.
TSMC and Samsung have already released astonishing provisional guidance, posting huge numbers that beat all estimates.
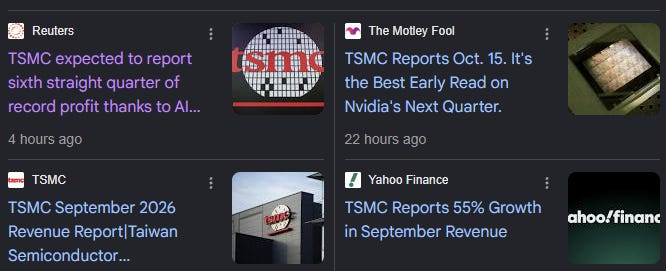

It is clear that the AI trade remains in full swing. This momentum should flow directly through to ASML. While ASML typically reports with a degree of caution and conservatism, TSMC has reaffirmed its commitment to ASML’s ultra-high EUV technology. The structural tailwinds here remain firmly intact.
HEALTHCARE AND MACRO
We will also get a pulse check on the healthcare sector with earnings from UNH 0.00%↑ UnitedHealth and JNJ 0.00%↑ Johnson & Johnson, which will offer a read on the pharmaceuticals space and general lifestyle health trends.
On the macroeconomic front, the main figure I’ll be watching this week is the U.S. Inflation Rate. This is the key data point that will dictate the Federal Reserve’s next moves on interest rates.


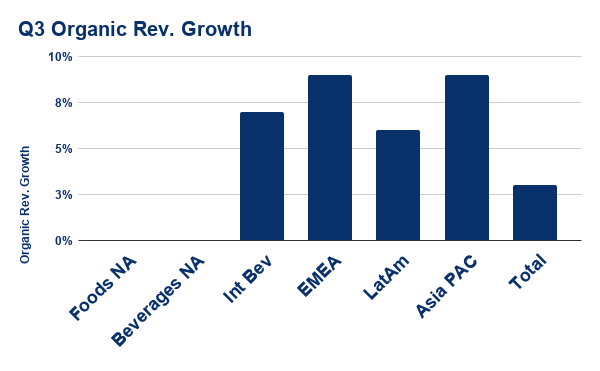
We may already be seeing the story unfold through corporate earnings - for instance, Pepsi recently noted that its North American division is struggling, hinting at an increasingly price-sensitive consumer.
PEPSI Revenue Growth Q3 2026
Upcoming Events & Reading
Breaking Waters Live Q&A: Next week, we are speaking with Andrew Hollingworth of Holland Advisors. Andrew is an excellent, high-conviction fund manager who targets founder- and owner-managed companies. It’s going to be a fantastic conversation. Sign up for the live Q&A here: www.bit.ly/highconvictioninvesting.
Book Club: Don’t forget, we are currently reading Buffett’s Early Investments. I am thoroughly enjoying it, so make sure you pick up a copy. We’ll be speaking to the author, Brett, in November!

Stay nimble, and let’s see what the data brings.


